For pre-retirees and retirees
Get Retirement Healthy
The Retirement Health Check is a 20-minute phone call where we walk through all three against your actual situation. No cost. No obligation. No pitch at the end.
What we cover in 20 minutes
How can you maximize your income in retirement?
Which accounts you draw from first, when to claim Social Security, and whether your withdrawal rate survives a bad first decade.
How can you lower your tax bill?
Roth conversion windows, the gap years before Medicare and RMDs, and the tax bill your beneficiaries inherit along with the account.
How can your investments be optimized?
Whether your allocation matches the income you need, what you are actually paying in fees, and the concentration risk you may not know you are carrying.
See your own numbers
Move the sliders. Nothing is saved and nothing is sent. This is a simplified illustration, not a plan, and it is built to show you where the questions are.
All calculations run in your browser. No data leaves this page.
Of your $1,900,000, roughly $1,760,000 is yours.
The rest is a tax bill you have not paid yet. How large it ends up being depends almost entirely on when you take the money out, not how much you have.
Order of withdrawals: two paths from the same starting point
Portfolio value from retirement to age 95 under two withdrawal strategies.
Same portfolio. Same spending. Different order of withdrawals. The only variable that changed is sequence.
You have a window between the paycheck stopping and required withdrawals starting.
Based on what you entered, you have roughly $337,059 of unused room in the 12% and 22% brackets across those years. Income you do not recognize during that window does not disappear. It comes back later, taxed at whatever rate applies then, on top of Social Security and required minimum distributions.
Year-by-year distributions, coordinated approach
| Age | From taxable | From pre-tax | From Roth | Social Security | Gross income | Taxable income | Marginal | Federal tax | After-tax income | Ending balance |
|---|---|---|---|---|---|---|---|---|---|---|
| 65 | $23,716 | $94,865 | $10,164 | $0 | $128,746 | $67,413 | 12% | $6,554 | $122,192 | $2,598,140 |
| 66 | $24,309 | $97,237 | $10,418 | $0 | $131,964 | $69,099 | 12% | $6,718 | $125,247 | $2,589,485 |
| 67 | $16,634 | $66,535 | $7,129 | $45,646 | $135,943 | $73,593 | 12% | $7,566 | $128,378 | $2,624,146 |
| 68 | $17,050 | $68,198 | $7,307 | $46,787 | $139,342 | $75,433 | 12% | $7,755 | $131,587 | $2,658,171 |
| 69 | $17,476 | $69,903 | $7,490 | $47,956 | $142,825 | $77,319 | 12% | $7,949 | $134,877 | $2,691,467 |
| 70 | $17,913 | $71,651 | $7,677 | $49,155 | $146,396 | $79,252 | 12% | $8,147 | $138,249 | $2,723,938 |
| 71 | $18,361 | $73,442 | $7,869 | $50,384 | $150,056 | $81,233 | 12% | $8,351 | $141,705 | $2,755,479 |
| 72 | $18,820 | $75,278 | $8,066 | $51,644 | $153,807 | $83,264 | 12% | $8,560 | $145,247 | $2,785,982 |
| 73 | $19,290 | $77,160 | $8,267 | $52,935 | $157,652 | $85,345 | 12% | $8,774 | $148,879 | $2,815,327 |
| 74 | $19,772 | $79,089 | $8,474 | $54,258 | $161,594 | $87,479 | 12% | $8,993 | $152,601 | $2,843,391 |
This runs to age 95 in the full analysis. The version here stops at ten years because the years that matter most for tax planning are usually the first ten, and because past that point the assumptions do more work than the math does.
Where each kind of holding belongs
Bonds, REITs, and high-turnover strategies. Their income is taxed at ordinary rates anyway, so sheltering it costs you nothing and saves the drag.
Broad equity holdings with low turnover. They generate qualified dividends and long-term gains, they can be harvested for losses, and they receive a step-up in basis for your heirs.
Your highest expected growth holdings. Everything they earn from here forward comes out untaxed, so this is the account you want compounding hardest and spending last.
Two people can hold identical investments and end up with materially different after-tax results based only on which account each holding sits in. This is one of the few decisions in investing that is fully within your control.
Order of returns, same average
These two portfolios earned the exact same average return. The only difference is that one had its bad years early. If you are withdrawing while that happens, the order of returns matters more than the average, which is why the first five years of retirement get built differently from the twenty after them.
What this does not know about you
This ran on four numbers and a few assumptions. It does not know that you are planning to sell the business in three years, or that one spouse will keep working until 68, or that there is an inherited IRA with a ten-year clock running on it, or that a third of the pre-tax balance is in company stock with a cost basis from 1994.
Those details are usually where the real money is, and they are also the reason a calculator cannot answer this properly. The 20-minute call is where we look at them.
On the call you tell me where you are and what is keeping you up at night. I tell you what I would look at first and what I think you are missing. If we are not the right fit, I will say so and point you somewhere better. There is no presentation and no second person on the line.
If it makes sense to keep going
Retirement Health Check · 20 minutes, by phone
The call above. Most people stop here, and that is a fine outcome.
Discovery meeting · 60 minutes
We go deep on your goals. Beforehand you send us statements and your most recent tax return, because we cannot say anything useful about your taxes without seeing them.
Plan review · 60 minutes
We come back with written answers to the three questions, built on your real numbers. You keep the analysis whether or not you hire us.
There is no obligation at any step, and nothing is signed until step three is behind you.
Who this is built for
This is a fit if:
- You are within ten years of retirement, or already retired
- You have saved enough that taxes are a real problem and not a rounding error
- You have a tax bill coming that you have not planned for: large pre-tax balances, a business sale, concentrated stock, or an inherited IRA
- You want someone who coordinates the whole picture, not just the portfolio
This is probably not a fit if:
- You are looking for stock tips or someone to beat the market
- You want a one-time answer to a single question with no ongoing relationship
- You are more than fifteen years from retirement and still in pure accumulation
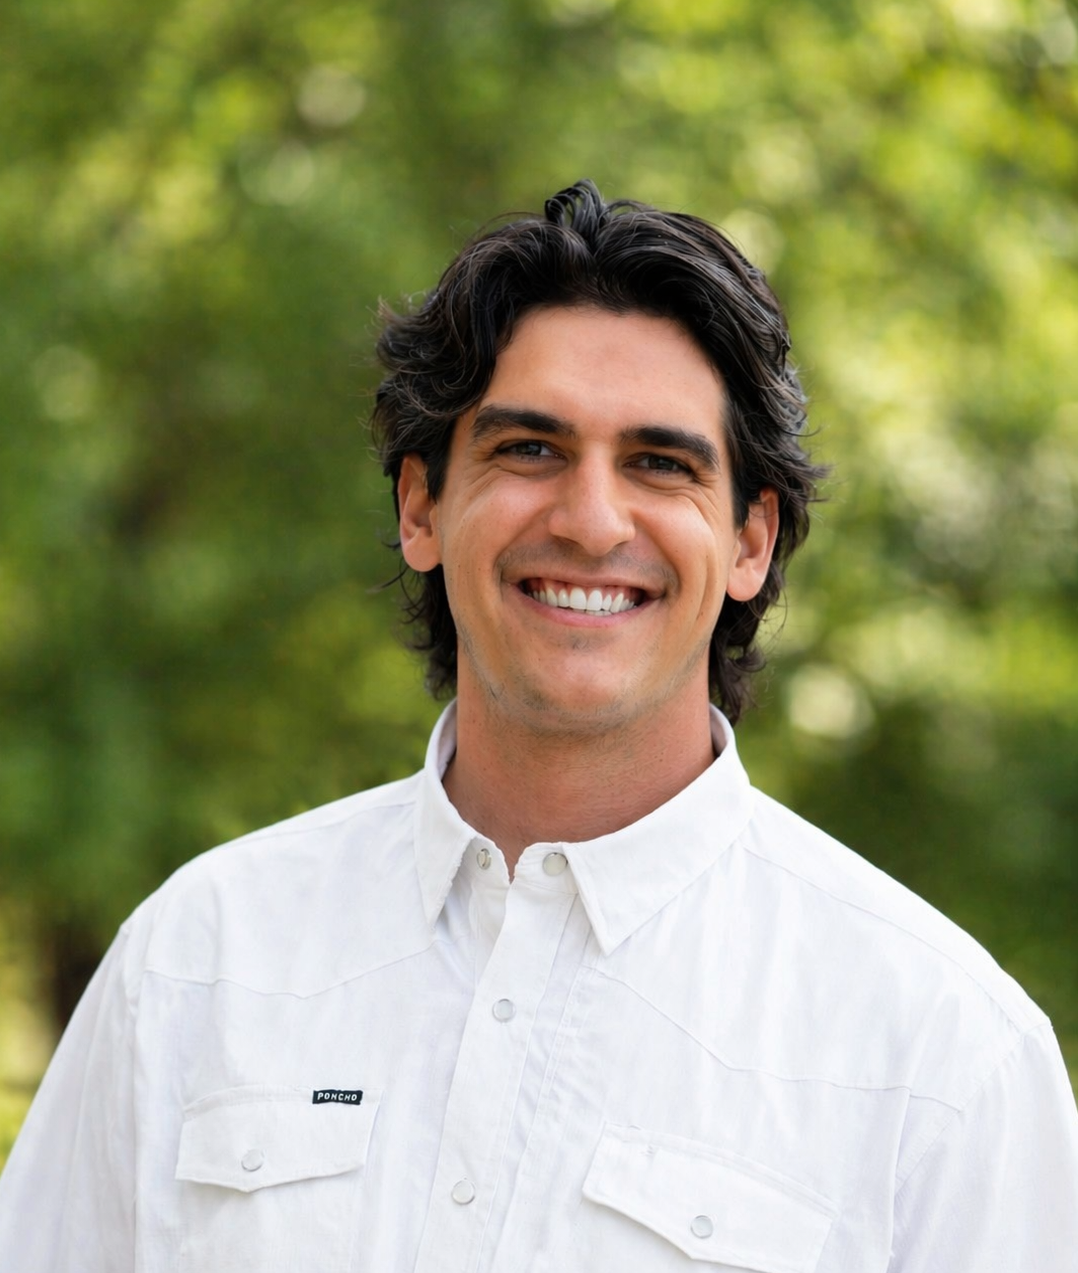
Conner Young, Founder, Baskets Capital
I built Baskets Capital in Austin to do one thing well: help people who spent thirty years saving figure out how to spend it without handing an unnecessary amount to the IRS. We are a fiduciary registered investment adviser, our clients' money can be held at multiple custodians.
Pick a time
Twenty minutes. Pick anything that works, evenings and early mornings are on there too.
Not loading? Book directly on calendly.com
Prefer not to use the scheduler? Book directly at calendly.com or call 737-210-3054.